FINANCIAL CLARITY + OPERATIONAL STRUCTURE
Understand what is happening in your business before you decide what to do next.
The Owner's Advocate helps Filipino business owners and serious solo operators make sense of their money, operations, and next decisions - using practical diagnosis, structured plans, and focused systems.
For small business owners, agency founders, professional firms, and serious solo operators.
The simple version
When the business is busy but unclear.
TOA is for owners who are earning and working hard, but still cannot clearly see what is creating pressure.
Where is the money actually going?
What is making work harder than it should be?
What needs to be fixed first?
What is the most practical next step?
FINANCIAL CLARITY + OPERATIONAL STRUCTURE
For owners who have real activity, but need a clearer way to run it.
TOA is not general business coaching, bookkeeping, BIR filing, or a generic slide-deck consultancy.
It is structured, principal-led work for business problems involving money, operations, and decisions.
01
Small business owners
Your business is running, but cash, priorities, and daily decisions still feel too dependent on you.
02
Agency and firm founders
You have clients and a team, but handoffs, workflow, visibility, or operating rhythm are becoming difficult to manage.
03
Serious solo operators
You earn real income but need clearer separation between business money, personal spending, taxes, and owner pay.
HOW TOA WORKS
Start broad when the problem is unclear. Go focused when the problem is specific.
If you do not yet know what is causing the problem, you can inquire about a Clarity Audit. If you already know the specific area you want to improve, browse the Focus Areas catalog under Services.
Understand the situation
Build a practical plan where needed
Install one defined system when the issue is localized
HOW TOA WORKS
Direct advisory support for business problems that need more than a template.
These are TOA's four core service levels. You may inquire about any level,
but the final scope is determined by what the business actually needs.
L1 · Diagnostic
Clarity Audit
For when you know something is off in the business but cannot yet name the real problem or the right next step.
₱12,000 fixed fee
One-time diagnostic. No retainer.
L2 · 90-day plan
Operating Blueprint
A practical, custom 90-day plan for a business that needs a clear sequence of changes, priorities, and working tools.
Starts at ₱35,000
Clarity Audit may be required first.
L3 · Ongoing support
Principal Oversight
For owners implementing an existing TOA plan who need accountability, review, and decision support over time.
₱25,000 / month
Three-month minimum. Limited capacity.
L4 · Focused system
Modular Systems
For one specific financial, operational, or strategic bottleneck that can be resolved through a bounded project.
₱25,000 / module
One defined lane. One-time project.
Not sure which flagship service fits? Use the Inquire button and describe what is happening. You do not need to diagnose your own business before reaching out.
Focus Areas
Business problems you can address one at a time.
Each Focus Area can eventually include a free guide, a DIY tool, and direct TOA support. Available projects have active buttons. Projects still in development are marked Opening Soon.
Choose your level of help
Learn it. Do it yourself. Or request direct help.
If the problem is specific, start with the relevant Focus Area. If your situation involves several connected problems, use Inquire or request a Clarity Audit instead.
Business Decisions
Capital, viability, pricing, planning
01
Capital Readiness
Available now
Clarify your actual cash position, funding need, repayment capacity, and operating readiness before taking on debt, seeking investors, or committing capital to a major move.
02
Break-Even and Payback Analysis
Check the break-even point and payback period before committing to a new product, project, service, or branch.
03
Costing and Pricing Decisions
Understand the real cost of your work and set prices that protect margin and make business sense.
04
Feasibility Research
Review whether a business idea, expansion, or planned move is workable before more money and time are committed.
Money Systems
Records, cash, obligations, visibility
05
Accounting System Setup
Set up simple records that can produce useful monthly income, balance-sheet, and cash-flow views.
06
Business Cash Flow Management
Track cash coming in and out, see upcoming obligations, and protect working capital with clearer rules.
07
Budgeting and Obligation Visibility
Separate fixed obligations, flexible spending, and owner draws so money decisions are easier to see.
08
Financial Statement Analysis
Understand what your financial statements are actually saying about margins, costs, profitability, and cash movement.
Operations Systems
Client flow, work, people, controls
09
Client Onboarding System
Create a clearer process from client payment or confirmation through intake, briefing, and project kickoff.
10
Internal Workflow and Task Tracking
Move work out of chat and memory into a simple system that protects team bandwidth and project visibility.
11
SOP Creation for Recurring Tasks
Document repeatable work so the business does not stop whenever one person is unavailable.
12
Owner Weekly Planning System
Protect the owner's priorities by separating strategic work from recurring administrative demands.
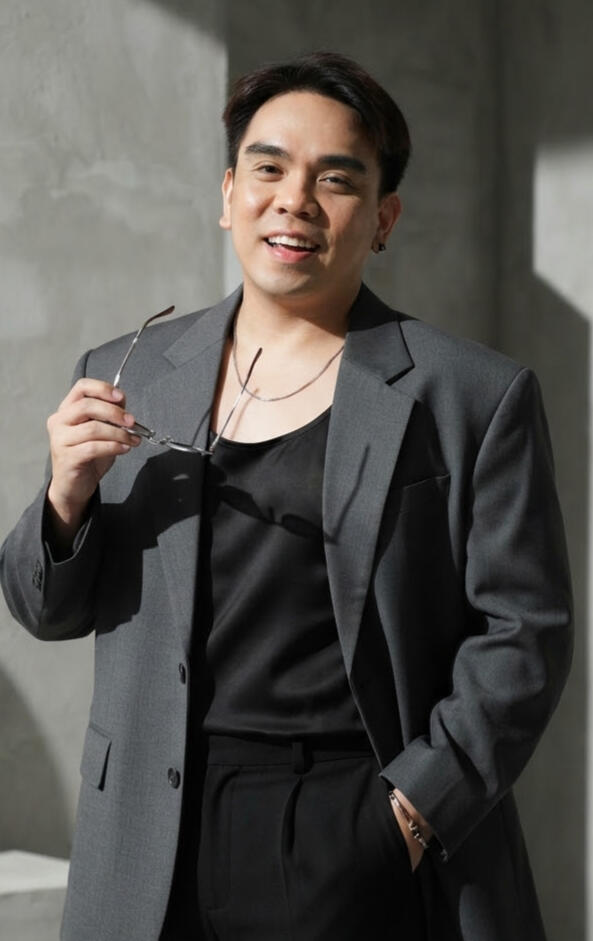
ABOUT
Leandro "Aian" Bauzon
Aian is the Principal Strategist behind The Owner's Advocate. He works with business owners and serious solo operators who need clearer financial information, practical operating structure, and better decision support.TOA work begins with the business as it actually is: its records, operating habits, constraints, decisions, and bottlenecks. The aim is not to give a generic framework. The aim is to identify what matters, decide what to fix, and build something the owner can actually use.
TOA thinking
Clarity before activity.
TOA is built for owners who need useful decisions and working systems
not more noise, generic advice, or a slide deck with no practical next move.
Start with what is real
Existing records, current workflows, actual constraints, and candid owner input are more useful than a polished version of the business.
Do not solve the wrong problem well
A visible symptom is not always the real bottleneck. Diagnosis matters before investing effort, money, or attention.
Build for use, not display
The intended output is a practical decision, tool, system, plan, or operating rule that can be used after the engagement ends.
TESTIMONIALS and CASES
“Leandro gave me the clarity and structure I needed at a pivotal stage. He helped me identify my real concerns and move forward with a clearer vision and concrete next steps.”
— Harchie M., RPm
MA Clinical Psychology,
UST Graduate Student
“The session helped me pause and see more clearly where I am and where I can go if I commit to the right changes. I came away with renewed direction, stronger self-awareness, and a clearer sense of how I need to lead.”
— Jane P.
Unit Manager, AXA Philippines
"His guidance gave me clearer priorities, practical solutions, and a better way to think about systems in both business and personal life. It helped me focus on what truly matters and manage my work more effectively.”
— Jose T.
Founder, Sulit-Divi
CASE #1
Launching a Retail Store With Almost No Runway: A Clarity Audit Case Study
How The Owner’s Advocate helped a business owner see that his real problem wasn’t marketing, but a dangerously thin cash runway and an overloaded life.
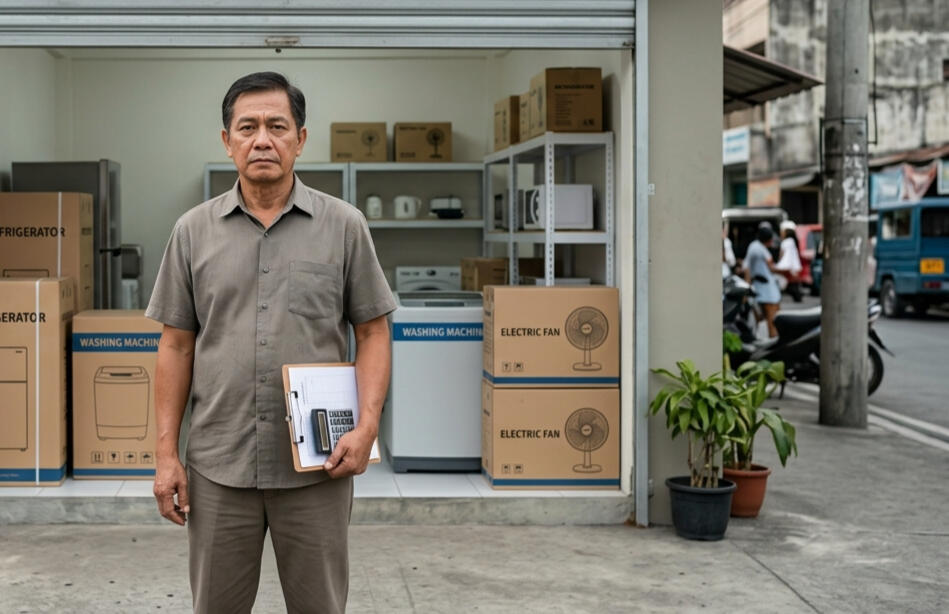
The situation: planning a store launch with limited capital
A Filipino business owner was preparing to launch a new appliance store in a busy area near a major mall. He had saved enough to cover upfront rent, basic construction, and an initial batch of appliances for display and sale.The same pool of money also needed to support his family while the store was still finding its footing. At the same time, he was still juggling several roles: part‑time paralegal work, an insurance manager position he wanted to keep, and most of the load at home as a primary caregiver.On paper, the plan felt tight but doable. As long as the store produced “strong enough sales” from the first month, he believed the business could pay its operating expenses, roll profits back into inventory, and grow.He approached The Owner’s Advocate for a Clarity Audit focused on cashflow and capacity before finalizing the launch.
What the owner believed the problem was
From his point of view, the main questions sounded like classic marketing and sales concerns:“How do I make sure the launch is strong?”“How do I attract enough customers quickly so the store can pay for itself?”He saw the challenge primarily as a sales and marketing problem. If he could bring in enough walk‑in customers and hit the daily sales target, he expected everything else to follow: rent covered, staff paid, inventory replenished, and profits reinvested.He also assumed that future money from a planned land sale and possible investors would arrive within two to three months. That future capital was treated as a safety net that could extend the runway or fund a micro‑lending line connected to the store once operations were running.In his mind, the risk was: “What if sales are not strong enough?”
The deeper question—“What if the runway itself is too short?”—had not yet been fully examined.
What the Clarity Audit revealed: no real cash runway
When we ran a Clarity Audit, we did not begin with marketing tactics or store layout ideas. We started by examining three core elements of his situation: the capital engine, the operating structure, and his actual human capacity to carry the plan.The diagnostic process surfaced several key findings.1. The capital looked big enough on paper, but not in reality
After mapping his planned spending, we found that:A large portion of the money would go into rent deposits, basic construction, and initial appliance inventory.The amount left over for household expenses was thin and might not reliably cover even one full month of real‑life costs: food, transport, small emergencies, and other day‑to‑day needs.In other words, the store setup consumed most of the available cash, leaving very little runway for the family if anything went wrong in the early months. There was almost no buffer for a slow launch, delayed sales, or unexpected expenses.2. The launch plan assumed high performance from day one
The original plan expected the store to:Reach its target daily sales level almost immediately.Operate near a major mall and compete with established stores straight away.Generate enough revenue in the first month to pay rent, cover utilities, service staff costs, and restock appliances.However, there was no hard evidence yet that walk‑in demand in that specific location would hit those levels in the first 30–60 days. The plan was essentially built on optimistic assumptions about customer traffic and early sales.3. The same cash pool was responsible for both business and family survival
The Clarity Audit found that his business capital and family money were still mixed in practice. This meant:The same pool of money was expected to fund store setup, inventory, and early operating costs.That exact same pool had to cover rent or mortgage at home, food, school‑related expenses, and other personal obligations.If the store underperformed in the first month, the family’s daily life would immediately feel the impact. There was no separate emergency buffer or protected reserve.4. Capital leakage made the runway even weaker
We confirmed that there were existing patterns that could quietly drain capital:Gambling habits that pulled from available cash.Unplanned financial “help” to relatives and friends, often given from the same funds meant to protect the business and household.Without firm boundaries on these behaviors, any early sales from the store were at high risk of being diverted before they could stabilize inventory and working capital.5. The owner’s role stack made the plan fragile
Beyond the numbers, the Clarity Audit looked at his operating capacity as a person:He was already working as a part‑time paralegal.He was holding an insurance manager title, trying to keep the role active.He was carrying most of the responsibilities at home.He wanted to add “hands‑on retail owner” to that stack.This level of role stacking left almost no mental or physical bandwidth for the realities of running a demanding physical store: managing staff, monitoring inventory, handling customer issues, communicating with suppliers, and solving problems in real time.6. Legal and regulatory risk could erase the setup overnight
Because of the location and cost pressures, there was a temptation to operate with incomplete permits during the early months.The Clarity Audit flagged that launching near a major mall without full permits exposed him to the real possibility of being asked to stop operations or face penalties, which could instantly destroy the money already locked into rent, fit‑out, and inventory.The structural break
When the findings were put together, the structural break became clear:The launch plan was built as if the business would perform at a high level from day one.The cash and human capacity were set up as if there was no room for delays, mistakes, or slow sales.That mismatch meant the plan was not just risky. It was structurally fragile.
The diagnostic work: how The Owner’s Advocate approached the case
The Owner’s Advocate ran this engagement as a Clarity Audit focused on cashflow and capacity, not as a generic business coaching session.The work followed a structured diagnostic flow.Step 1: Build a grounded picture of the capital engine
We first established a clear, simple picture of the capital engine:How much cash was truly available after rent deposits, fit‑out, and initial inventory.What the minimum monthly burn looked like for the household and for the store.How long the combined business‑plus‑family structure could survive if the first month was flat or below target.This converted a “gut feeling of enough” into a concrete view of runway length—in days and weeks, not just in abstract comfort levels.Step 2: Separate perceived reality from verified reality
We then documented the situation from two angles:Perception side:The capital felt enough to secure the space, set up the store, bring in inventory, and leave something for household needs.The expectation was that strong sales and future money from a land sale and investors would support the plan.Verified reality side:After setup, the remaining cash for the household was thin and could easily fail to cover a full month of real‑life expenses.There was no proof yet of early sales strength.Critical roles and responsibilities were already consuming most of his available capacity.Putting these views side by side made the gaps visible in language the owner could immediately understand.Step 3: Name the systemic frictions clearly
We defined three main systemic frictions and wrote them down in plain words:Capital leakage and weak boundaries – personal habits and unplanned generosity drawing from the same cash meant to protect the business and family.No real runway – a launch model that assumed strong immediate performance with almost no financial cushion for slower months.Fragmented roles and execution – trying to carry multiple serious roles at once, leaving no attention left for demanding store operations.By naming these frictions explicitly, we turned vague “worry” into concrete operating risks that could be addressed.Step 4: Reframe the core question
Before the Clarity Audit, the owner’s main question was essentially:“How can I maximize this launch and get strong sales quickly?”After the diagnostic work, the more accurate and useful question became:“How do I avoid a launch structure that could quietly burn through my family’s last 30–60 days of usable cash?”This reframing shifted the focus from aggressive growth to protection of capital and family stability.
The new decision path: designing a safer 90‑day approach
The Clarity Audit did not simply tell the owner “Do not launch.” It mapped out what a safer approach would need to look like if he still wanted to move forward in any form.Key implications included:The current scale of the store—inventory level, fixed costs, and expectations—was too aggressive for the actual capital runway available.His existing behaviors around money needed clearer boundaries if any business capital was going to survive the first quarter.The role stack had to be reconsidered; he could not realistically be a fully engaged retail owner while also trying to keep multiple other roles and heavy home responsibilities without something giving way.The outcome of the engagement was decision clarity, not a forced direction:He could see, in writing, what was likely to happen to both the business and the household if he launched at the planned scale without changes.He understood that even perfect marketing would not fix a structural cash and capacity problem.He had a concrete basis to either scale down the launch, restructure the plan, slow down, or delay until his capital and life were truly ready.The real win in this case was not a feel‑good launch story.
The real win was avoiding a launch that would have quietly erased his family’s financial safety margin in the first 30–60 days of operation.
Who this Clarity Audit case speaks to
This case is relevant if you recognize yourself in any of these situations:You are planning to launch or expand a physical store, but you are not sure if your capital is enough to survive a slow first 90 days.Your plan depends heavily on future money—loans, investors, or asset sales—that is not yet in your account.Your business capital and family money are still effectively mixed, even if they are in different accounts on paper.You are already carrying multiple roles and responsibilities, and you are adding a demanding business on top of that.In these conditions, your biggest risk is often not “poor marketing” or “lack of hustle.”
Your biggest risk is launching a structure your cash and your life cannot actually support.The Owner’s Advocate exists to help you see that structure clearly before you commit, so you can protect your capital, your family, and your sanity while still building something real.
Get the Capital Readiness DIY Tool
The Capital Readiness DIY Tool is a self-guided digital resource for business owners who want to understand their current capital readiness, organize the relevant information, and identify what needs attention before seeking financing or additional capital.Price: ₱1,499Your purchase includes the DIY tool, supporting source materials, and a DIY Buyer Credit that may be applied to a qualifying Capital Readiness service request, subject to the terms below.
How to purchase
1. Send your payment
Transfer ₱1,499 using either of the payment options below.
Text[Option 1: Bank transfer]
Bank: Union Bank
Account name: Leandro Bauzon
Account number: 1094 2931 4225
[Option 2: GCash / Maya]
Account name: Leandro Bauzon
Mobile number: 0919 3456366
2. Send your proof of payment
Email your payment confirmation, receipt, or transaction screenshot to: [email protected]
Use this subject line:
Capital Readiness DIY Tool — [Your Full Name]Please include:
1. Your full name
2. The email address where you want to receive the materials
3. Your business name, if applicable
4. Your payment reference number
3. Receive your materials
After payment verification, your Capital Readiness DIY Tool, source materials, and DIY Buyer Credit details will be sent to the email address you provided.
Delivery timing
Payments are reviewed on business days. Please allow up to one business day after payment verification for delivery. If you have not received your materials after that period, email [email protected] with your payment reference number.
DIY Buyer Credit: ₱1,499 credit toward the Capital Readiness direct service, valid for 60 days from purchase, usable once, non-transferable, and redeemable only after the buyer submits a service request and TOA confirms fit and availability.